Showing posts with label budget life. Show all posts

Target Haul

>> Thursday, January 25, 2018

As I always say, I'm a work in progress. I write one day about spending too much at Aldi, and today I'm sharing my Target haul. Confused much? I know. Anyway, I did take some stuff back from Christmas time, which is where I got the funds. These weren't entirely random purchases. Or, rather, that's how I'm rationalizing these buys. I hadn't been to Target in a good three weeks, though. So, this is progress.

Here's what I got:


The total cost was right about $50.

Which includes $12 of toilet paper.

Not pictured.

MODO dough looks really cool. It was around $5.50 per 3-pack. I realize that's expensive, but I do have a plan and reason I bought these. I actually often make my own play-doh. I found a great recipe, but I haven't had the best containers. Anyway, I saw these and I think they'll be perfect for filling with homemade doh once this stuff dries out, which it always does eventually. So far, I really like this play-doh stuff, though.

I got a pack of Valentines for Ada to fill out for her classmates. I'm actually volunteering at her class party this year. Excited for that. Anyway, I was in the $1 spot, which has turned into the $3-$5 spot in my opinion. I ran into a woman who had just moved to this country and she asked me to explain the whole Valentines thing to her. We had a nice chat and both decided on these.

Also in the $1 spot, I picked up a package of felt dollars and cents ($3). I figure the kids can use it when they play with their play kitchen. They often set up a shelf area like it's a mini store. I am also working on teaching Ada about cash and the value of money. Plus, I am a sucker for anything made of felt.

I got Ada a proper doll hairbrush ($5). She's been needing one for a while so her American Girl doll doesn't look like a hot mess. I am planning to write up a post on American Girl on a budget. Is anyone interested? I scored Ada's doll very gently used on Ebay. I have a lot of other tips. I feel they are very high quality and worth it.

Love Terra animals. I got Eloise a bear because she loves the bear on the Kodiak Cakes box. Very much like the more expensive brand -- love the weight and detail on these. Eloise will carry a single one around with her all day.

I needed a new set of measuring spoons. I decided on KitchenAid self-leveling ones. Can't go wrong with that added feature.

And then I swung by the makeup area and found that my favorite brand of cosmetics, Soap + Glory, had some stuff on clearance. I picked up bronzer for less than $4! Here's What's in My Makeup Bag these days, if you're curious.

Read more...

That Time I Spent $172 at Aldi

>> Wednesday, January 24, 2018

I used to boast that I could fill up a whole cart at Aldi and still come in well under $100. Well, I decided not to shop with a list a couple weeks ago. (That's grocery budget 101 stuff, Ashley!) And when I got to the front of the store and started tossing everything onto the belt, I realized I'd made a major mistake. It was one of those weeks when Aldi had, like, so many cool things that were those limited time buys. So, I got sucked in and stocked up.

And then: $172! Ahhhhhh! I was hoping for more like $100.

Here's what I bought:


I haven't gone over what our weekly food budget is in a while. It's been anywhere between $75 and $125 a week in recent years. As we examine our debt and budget options, we're still trying to figure out a number that would work well for us monthly. It needs to accommodate not eating out, school lunch stuff, and special things for our tiny toddler (because she NEEDS to eat, so sometimes I NEED to get her special stuff).

We've experimented with shopping once a month and had good success . . . so I realize that spending a ton at one time isn't always a reason to freak out. But this time was a mistake. A wakeup to get meal planning again. I do actually meal plan each week, but it's been very rough lately.

Anyway, this story had a happy ending. I was able to get groceries for like $65 this week, making the total $240 for the two weeks -- or -- $120/week. I think this sounds like a realistic grocery budget for us. I may bump it to $125 -- or -- $541 a month. Of course, the pay-off-our-loans girl in me says maybe we can shave it down to $500 a month.

But I need it to be realistic and leave some room for wiggle. We try our best to eat a variety of fresh fruits, vegetables, whole grains, etc. And without eating out, we like to cook a couple "fun" meals each week so we don't feel too deprived.

What I've found in my years of writing about our food budget is that grocery costs vary WILDLY across the country (and world). So, these figures may sound either astronomical to you or like "how can you even feed your family" on that amount. I get that. So, no judgement. I'm just sharing our struggles and triumphs with this stuff.

Whatever the case, I'm glad we're back into the rhythm of buying most everything at Aldi. There are still a few items we cannot get there. Tofu comes to mind. But resisting Wegmans has already lowered our food costs by quite a bit.

Do you have a grocery budget or just buy whatever? How do you figure out how much to spend? Do you end up revisiting the budget often -- like we seem to do?

Read more...

Why We’re So Bad at Saving Money, etc.

>> Wednesday, September 27, 2017

I’ve been mulling over a lot since I last wrote about our budget and desire to get out of debt. At the time when I wrote, Stephen was still home for summer break, and I was basically milling my own grain to bake homemade bread daily, cooking up fresh batches of yogurt + cheese, and generally being a model homesteading mother. I love this stuff. It’s the stuff of my life that brings me a lot of happiness. As the pace of life has picked up (here's our day in the life) with the start of school and coaching season, however, I have had a lightbulb moment.

It won’t shock any of you. But I’ve realized WHY we are so horrible at saving money even when we have the best of intentions. When life is slow and time is, well, plentiful, we have lots of energy to expend. Energy equals dollars, quite honestly. When I have lots of energy, I’m able to keep my house clean, I’m able to cook homemade meals, I’m able to mix together all my own household cleaners. When I have more energy and time, I am able to think of more ways to save money.

Heck, I’m able to think, period.


When energy and time are taken out of the equations, that’s when convenience enters. Again, this isn’t mind-blowing by any means, but when you’re just surviving everyday life . . . it can be hard to pinpoint why exactly, say, you’re driving to get a bagel and coffee (and you don’t even like coffee) in a haze and then somehow also want to fork over $20 or more for takeout on a Wednesday evening. And then your mind is made up that you may never cook again.

Convenience has both good and bad connotations, doesn’t it? 

It means easy-breezy and comfortable. 

It also means waste (packaging, money, etc.) and laziness. 

What am I talking about? Well, packaged foods and beverages come to mind. Takeout and heat-up meals are another offender. Then there’s stuff like paper towels, which we actually have successfully broken the habit of using. Then there’s this grey area of just buying things -- no matter what they are -- in the moment because they’ll help you in some way. Perhaps this is my own emotional purchasing, but like buying a small toy because my kid won’t stop screaming due to teething, and I think it will help.

Where am I going with this?

OK. So, all this stuff costs money. Time equals energy to do things like making laundry detergent, baking bread, and generally being less wasteful. When I don’t have time, I spend lots of money for both practical and emotional reasons. And then it’s this vicious cycle that’s difficult if not impossible to break. Even harder because our society seems set up to drive us into consumerism by default.


So, how to combat this issue?

One thing would be to somehow get more time. Are you snickering? I am. I think all of us would love to find the magic that would provide this luxury. Getting up earlier has certainly given me more time, but I’m using that time for work and exercise right now. Alright, then there’s having more money. LOL again. How about getting more energy somehow? I know a lot of people drink coffee. I go in phases with the stuff. I’ve mentioned it before, but it actually gives me a headache, so I’ve tried tea . . . but it doesn’t give me much of a boost. I also don’t want to be dependent on some substance all the time.

In the absence of more time, money, and energy, I think all that’s left to do is to resist the urge to give in to all conveniences. Some, sure. But I think it’s a slippery slope once you get going. Or at least once I get going, it seems like one convenience leads to another. Resist is such a heavy word. It sounds difficult and laborious. And that’s exactly what it is. Beyond resisting, I suppose it's finding balance and also finding faster ways to do the things that will make all that homemade stuff more convenient.

I had written up a series a while back, Green in 15. I suppose I need to take a lesson from myself. As an aside, I’m sure you’ve realized by now that bloggers are no more expert at anything than you are. We just like to talk and take photos of things we often do for the first time and find groundbreaking. To be fair, there are plenty of things I’ve shared in this space that I’ve honed for years and years. But there are definitely a few I’m guilty of jumping the gun on sharing.

Back to my original thoughts:

A.) I can’t do it all. I need to give myself grace if I give in to things that make my life easier. Even if that means temporarily creating more waste and spending more money.

B.) Not everything has to take such a long time. Maybe there are even some smart hacks I could try on my old methods to make my favorite DIY stuff.

C.) I can look at one thing at a time. Maybe some weeks, I just need a clear goal. Like cooking all our meals at home could be first. It doesn’t have to be difficult. I could get back into batch cooking or freezer meals. After that, I could nudge myself out of the freezer aisle and stop buying more prepared foods at insane markups. The next week, I could try out a dry laundry soap recipe that takes less time than the one I mix together by boiling. Etc.

How do you deal with this situation in your everyday life? Have you triumphed over the time/energy trappings? I’ll be sure to report back on my progress. 

Read more...

6 Debt Lessons from Readers // Debt Free

>> Wednesday, September 6, 2017

I wanted to take today to thank all of you for your advice on our money situation. So many readers have either commented on the blog or Instagram, or sent me private messages about what they did to start their own debt-free journey. It’s helpful for a few reasons. First, it makes us feel much less alone. I don’t know why, but we sometimes assume we’re the only people dealing with money issues. We see people jetting off on expensive vacations, buying much fancier houses, sending their kids to snazzy private schools, living vacation fantasy lives, etc. and we assume we’re the only people in the red.

But you know what they say about when you ass--u--me things.

In the end, it’s good to focus only on us because that’s what will get US out of debt. I think focusing on other people can only be harmful in some ways because -- despite how we’re pretty good at avoiding this trap -- there’s this whole peer pressure component to life, right? Keeping up with the Joneses, even if you aren’t in that game. It sort of filters into the subconscious. Of course my kid should have X, Y, and Z. Of course we deserve X, Y, and Z. But a lot of this stuff means living above means, etc.

As a silly example, Stephen and I are both feeling like we should not have immediately gone out and replaced our central air system last year. I know why we did -- we had just brought Eloise home, my hormones were saying YES WE NEED IT NOW, and we had grown accustomed to having it, like many other people have in our area. But if we’re being honest, we could have popped a few window units in the bedrooms and probably been fine. After all, that’s how I grew up. That would have cost a few hundred versus a few thousand . . . and we may have been able to borrow some from family or friends for a year or two while we surveyed the options.

I digress.


The second reason it helps to hear from you guys is because some of you have DONE it. You’ve gotten out of debt, gone through the trials, and come out the other side to tell the tale. Hearing success stories and the hard work it took to get there is inspiring. Anyway, I wanted to condense some of the best tips/advice we received into a nice 6-point list.

// 1: Do get creative 


One reader pointed out that her house went up in value significantly since she bought it. She considered selling and using the profits to pay off debt. This is interesting because it’s something we’ve considered doing as well. We love our home, but we often feel like we could be happy in a smaller, less expensive house. That said, our own property value has stayed relatively stagnant, so I don’t think we’d gain much this way. Regardless, I thought this example was interesting. If you’re really in debt, you can do creative things . . . and even turn your thinking upside down about life. This is one reason, for example, the tiny house movement is so popular.

Other readers warn that investments like houses may be good ones to hold onto, especially if getting rid of your home significantly affects your quality of life. It’s a hard balance to strike. And this is just one way of getting creative. We’ve experimented with becoming a one-car family in the past. It’s something I wish we could stick to, but our area isn’t exactly pedestrian friendly and Stephen is gone a lot of the time for coaching.

// 2: Do give up extras


This is one area where I feel like we cycle between good points and bad. When you’re paying off debt, just cut the fat already. Stop going out to eat. Stop buying random stuff to fill your house or that emotional void (emotional shopper here!). Do pitch everything you can toward debt -- even if that means using Christmas money, etc. for a while. This isn’t to say you can’t EVER enjoy the finer things in life. But I know myself, and I often give into the whole “I deserve this” because of some insignificant accomplishment or pure laziness. Make meals at home, seek out free entertainment, keep your eyes on the debt-free prize.

// 3: Do remember that “small sacrifices add up”


I suppose this extends on the last tip, but it’s a different way of looking at just denying yourself things. A reader shared on my Instagram that “small sacrifices add up” and I liked that train of thought. It’s more positive than STOP ENJOYING EVERYTHING. Even if you can piece together one additional payment through giving up your daily coffee habit, it’s worth it. Gather together those pennies where you have them to save.

// 4: Don’t deplete savings. 


One of the popular debt-free methods encourages people to completely pay all money to the debt monster. But many of you shared that keeping zero or even just $1,000 in the bank for emergencies seemed like too little, especially with a family or house, etc. I agree.

How much should you keep? It’s personal and depends on where you live, your life situation, etc. Some say to keep $3,500. Others like to have a $5,000 safety net. We personally have about three months of our living expenses in our bank account. The reason for some much is because my income is variable. It’s tempting to shift this money around . . . but I feel like we’ve run into bad luck and needed these funds.

// 5: Do consider getting help


One reader mentioned that she and her husband see a financial advisor. I don’t know why this isn’t something we’ve considered in the past. But the advisor helped them figure out a game plan for attacking debt according to interest rate charges. Not only that, this advisor was also able to help the couple allocate funds toward their 401K and pay minimums on debt . . . but through some financial magic earn more interest on the 401K than was being charged on the debt, if I’m explaining that correctly.

// 6: Don’t get discouraged


This might be my favorite piece of advice. Don’t get discouraged if progress is slow. You may not be able to pay off massive amounts quickly. I feel like we’ve all seen the stories of paying off $100K in like six months. For many most people, this just isn’t feasible. Heck, we don’t quite make that much money . . . in a year. So not amount of scrimping or saving would give us that type of wild success.

Another reader explained that debt ebbs and flows throughout different stages of life. Don’t look at all setbacks as failures. I think that’s a good point to end this post on. If you have more to share, I’d love to hear you thoughts in the comments! I would like to add more of the tips into a part II post -- the next one will be some more specific things people shared about their debt-free adventures.

Happy Wednesday!

Read more...

Meal Plan, Takeout Fatigue, etc.

>> Tuesday, July 25, 2017

Before I get into the meal plan for this week, I don’t check Facebook all that often anymore. However, someone added me to a group that I do find quite interesting. It’s called the Non-Consumer Advocate. It’s all about finding ways to do things without necessarily spending money or otherwise consuming. Or if you do spend money, how to be smart about it. If you’re interested in that sort of thing, I highly recommend joining!

So, you’ve seen our $98 Aldi haul for this week. Our meal plan this week is nothing shocking or particularly interesting. I am trying to use up the things we have left over from vacation. (PS: Want more meal planning? Here’s the last time I wrote about this subject. And here’s all my posts on it.)


I’ll just be giving you the dinners we’re eating. Breakfasts are usually eggs and toast for Stephen, a protein smoothie for me, cereal + fruit for Ada, and waffles for Eloise. Lunch has been quite random as well this summer. I’m still trying to eat raw once a day, by the way. Should I do an update on that? Let me know in the comments!

Also: I’m trying to get Ada into more diversified eating, so I’ll try to touch on this subject another day. Snacks are things like Greek yogurt mixed with peanut butter, popcorn, carrot sticks, homemade granola bars, etc.

DINNERS


The girls will eat the veggie burgers, quesadillas, pizza, hummus, omelets, and Mexican quinoa dish with us. Or at least try. We also have some staples on hand for them, like mac and cheese or pierogis, if we think they won’t enjoy a meal (or if we’re eating at different times).


Thoughts on Eating Out


We definitely have takeout fatigue. I loved sampling cuisine from our favorite restaurants while on vacation. That said, it was mega-expensive (regrettably so!). And you know what? I missed cooking. I think we may even make better meals than some we get out. While a good meal out can certainly be a nice indulgence -- even a regular one -- I think we’re going to skip for a while. Even with my birthday coming up, a home-cooked meal seems much more pleasurable than anything else right now.

You get a lot of facts and figures if you look up how much the average family spends going out to eat each year. I estimate that we probably spend around $50 a week on an average week getting a mix of takeout, dining out, etc. That’s figured into our “entertainment” budget category. So, if we stopped doing that . . . that’s $2,600 a year. I only took the time to figure this out just now.

And now I feel a bit sick to my stomach. Do you know how many places that money could go? Holy moly.

What’s your policy on going out to eat? I doubt we’ll stop doing it altogether. But I’d like to save it for only special occasions. Maybe once a month? That sounds like cutting to the bone, but I think it’s doable. 


Recipe Liberation


Here’s my parting idea for the day . . . and it’s something I’ve neglected to mention on the blog. I rarely follow recipes (even my own) exactly. Well, if I have everything on hand, yes. But if I’m missing ginger for a stir-fry, for example, I’ll skip it. Of course, it’d be nice to get the extra flavor, but usually there are other spices + things that will do enough of the heavy lifting. If the ingredient is non-essential, like peppers for veggie quesadillas, I’ll leave it out, too. (This rule doesn’t apply with baking usually. Especially with things like baking powder, baking soda, etc.)

Anyway, I guess what I’m trying to explain is that cooking can be flexible. I am sure many of you know that. But I think some others think we must follow recipes exactly. Not the case at all! You can make all sorts of substitutions, swaps, and omissions. Heck, you can add things, too. It takes time to get cooking right. You’ll make missteps along the way. But you may even make something particularly delicious -- accidentally.

I’ll be back soon with a recipe for Greek salad, homemade granola bars, and some notes on getting back to from-scratch cooking and baking. Feels good.

Read more...

Bad Spending Month // Recovery Plan

>> Monday, April 3, 2017

March, you guys. Oh, March. Where to begin? Stephen and I are in the process of switching to a more local bank. We have most of our money (which isn't much!) in Bank of America, but there are no local branches. It's made the cash system costly. The month we did take out cash, we discovered that we were being double-charged. We had taken out our cash in two installments . . . and it ended up (FOOLISHLY) costing us like $30.

So, we joined a local bank which now makes ATM transactions free. In the process of switching, though, we haven't transferred around enough, so we decided to just do our debit card last month. I still shopped for our food at the beginning of the month in a large shop and stuck within budget. After that, though, it was a landslide of spending . . . and I'm really not proud of it. This is our current plan to get debt-free, and I hate already deviating from it.

Without having the physical money, we find ourselves venturing out to the store and buying all sorts of things we "need". We find ourselves without a plan -- and that's dangerous. I haven't looked at the ugly numbers yet, but I plan to do that later today. Part of me is actually just nervous/scared to look at how much we over-spent on our budget. Does anyone else ever feel that way when you're looking at a bad over-budget month?

Here's our plan for recovery:


Chatting about the Why


Stephen and I know very well why our spending got out of control. He started coaching track and is now gone long hours and Saturdays. This means we are trying to do anything and everything to make ourselves feel better. And that usually means eating takeout or getting extra food all the time. Because home-cooked meals are sometimes hard to make when life is crazy AND eating delicious sandwiches with fresh ingredients from Wegmans several nights a week just sounds . . . amazing.

Ugh. The schedule isn't changing until a couple weeks into June. If we keep spending at this pace, our bank account will look frightening by summer. This is one of the main reasons why everything went to crap this month. So, we need to recognize it and move on.

Going Back to Cash


We need to take out cash for this month. Period. I'm going to figure out the total number I want to take out today and then divvy it up into my cash envelope system wallet. Then I'm going to write out our spending plan for the month.. There isn't much more to say about this one. If you're prone to mindless and excessive spending when you use cards . . . cash can help so much.

Simplifying Our Meals


We have $500 a month set aside for our food. We have a pretty well-stocked pantry right now, so I may forgo the big monthly shopping trip and try to just use up what's in the pantry for as long as possible. I'll need to buy some fresh produce and other items that expire more quickly. But otherwise, I am going to try to plan our meals around what's already at home. This may mean eating pasta more frequently this month.

My goal is to spend just $300 of that $500. SAVINGS: $200, maybe more.

Planning a Personal Spending Freeze


I budget $200 a month to an allowance fund for the family. This money is essentially fun money, money for stuff each of us might need or want, and etc. This month of April we are going to try to spend as little of this money as possible. Along with that, we have a $135 monthly weekend fund to do stuff out. Instead of breaking into that, we're going to try to just doing free stuff on our weekends and skip eating out, etc. I'm hoping the nicer weather may help with this. Having a blizzard and all that jazz definitely contributed to us spending more money.

SAVINGS: Potentially $335, but we'll see what ends up happening. It definitely won't be all of this.

Changing Vacation Expectations


OK. Yeah. So, this is where it gets tricky. We are also heading up to Burlington to visit my brother mid-month. What I think may happen is that we use some of these weekend/personal funds to pay for what we are doing up there versus spending any extra on top of the budget. Does that make sense? We've had this trip planned for a while . . . and we originally intended to stay three nights. I think we're going to cut the trip back to just two nights and try to save that way as well.

On the trip, we get free breakfast at the hotel, so that's a savings. I'm going to look up as many free things to do as possible. And we will try to eat modestly out and not spend a ridiculous amount of money on all the meals. Gas is the other expense. I'll try to write more about our travel budget soon.

SAVINGS: $100 -- at least that's what we'll call it for now. It's complex because we didn't totally have budget for travel right now BUT we also want to see my brother and his girlfriend.

Postponing Paying Our Debt


This might not be a popular bullet point, but I think right now we need to preserve the money that's in our bank account. And that means skipping a month of paying an extra $1,000 to our debt. This isn't really a savings, but it will help us in the short-term preserve our emergency fund.

I am actually experimenting with taking on a bit less work this month because things have been crazy with Stephen's new schedule. Basically, we're needing to go back to our original pay-off plan to tweak it a bit. It may make better sense for our to try and allocate $500 a month toward debt versus a full $1,000. I am having trouble sustaining writing so much when Stephen has 11-hour weekdays and was gone from 8:00-5:30 on Saturday.

Final Thoughts


This isn't the most organized or most inspirational budget post I've ever seen. I more just wanted to get it out there. We had a bad month. We recognize that we cannot go back to our old habits. Back-sliding it just not fun at all, especially when it comes to finances. We are admitting we messed up. We are doing a few things to help recoup some of the extra we spent. And all we can do now is more forward and have a good month.

What do you do to recover from a bad spending month? Any suggestions for us? I'm off to see exactly what the damage is!

Read more...

Budget Life // Monthly Grocery Shopping

>> Monday, February 6, 2017

I shared over the weekend that I did my very first monthly grocery shopping trip. Phew. It took me two hours total -- which included driving from place to place -- so, it was definitely time-consuming. In the end, I think I really like this approach. I am going to need to see how it pans out for our meals this month (and for time savings overall). But this is the fun in sharing along the way.

Today I wanted to just cover some of the planning I did. I think I'll also do a video about the foods and meals we're making, but today I have a pretty bad cold. Nobody wants to watch me talk, sneeze, and sniffle, I assure you.

Money matters:


For those of you who are really interested, I have budgeted $500 a month for food total. I'd like to cut this lower, maybe to $400, but I thought I'd first see how it goes. The $350 goes to the month shop. And the remaining $150 is split up into $35 per week (this is on average throughout the year) for things that spoil.

Step zero: Clean your pantry and refrigerator.


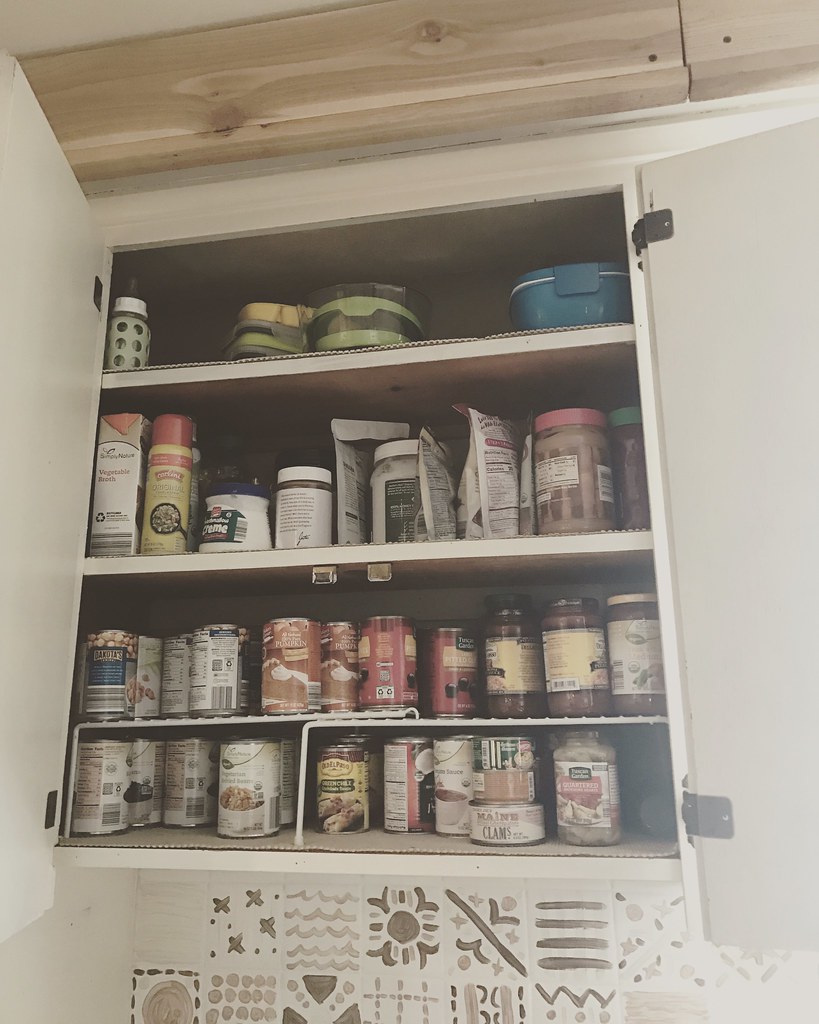
I took out all the spoiled and expired foods and tossed, recycled what needed to go. I also spent a great deal of time organizing my pantry to see what foods we DID already have to put toward meal planning this month. Taking stock like this will help you avoid over-buying and purchasing duplicates.

Here's my current food situation after the shop. I hope to do a quick post on how I organized my pantry by spending a mere $9 at the Dollar Store. (And, no. This isn't looking good for our less waste goal.)

Step one: Plan meals. Loosely.


And I really mean loosely. February has just 28 days in the month. So, I wrote out a menu that would give us breakfasts, lunches, and dinners for four straight weeks. I kept the recipes familiar for this first month. Things that we normally cook and enjoy, where I know the ingredients almost by heart. Some meals are on repeat during the week or month. Others are more free flowing.

I plan to share more about my meal-planning approach when I do my video!

Oh, and I uncovered this older post where I go through and share my favorite 18 vegetarian pantry essentials at Aldi. It's definitely worth reading if you're new to the store or just want to know some of the items I like to buy most every time I shop there.

Step two: Write down all the food you need. 


And it can be dizzying. I discovered that we may actually eat close to 96 eggs a month! That's insane to me (Stephen eats 12 per week, I do about 8 and Ada does about 4)! 60 slices of bread. 8 cups of mozzarella. I mean, it's really just tallying up everything that goes into your recipes and snack and making a gigantic list.

I then organized my list (after this one) by store and by section. It just helped me go through the aisles faster.

(BTW: I mean bucatini noodles down there!)


Step three: Price it out.


Now, here's where I failed this month -- but it wasn't totally my fault. I intend to shop at several different stores to get the best prices on my food. I do know that some of the stuff we like is only at Wegmans. And with some of the family pack foods, they have good prices on larger quantities of things like frozen fruit. Wegmans has a handy app where I had planned to price out my food ahead of time, but for whatever reason, it wasn't working the day I needed to use it.

Alright, but what do you do for stores that don't offer an app? Take scrupulous notes.

I jotted down some prices at Aldi during my shopping trip so I can consult them before next month's trip. It's going to be a lot of trial and error. But the important thing with pricing out stuff ahead of time is so it jibes with the cash system. I don't want to get to the register and suddenly realize I don't have enough money and -- gasp -- have to use my card.

Step four: Go to the store prepared.


One of my Instagram followers promptly pointed out that I didn't bring enough reusable grocery bags on my trip. My bad. Yes. In the very days after posting our desire to be a less wasteful family, I brought home a bunch of plastic grocery bags.

The thing is, I didn't plan ahead. I've never done monthly shopping, though, so I can't be too hard on myself. Now that I do think I enjoy this process, I hopped on to Amazon and picked up this set of mesh grocery bags and some more bulk produce bags to take on my trips. Stephen also accidentally ran over my favorite folding market basket in the garage. So I may need to get another one of those.

Lesson learned.


Step five: Dive in!


I just went for it. I was kind of nervous about how this whole shopping once a month would go. I don't feel like I did my planning perfectly. I worried maybe I wouldn't get enough food. Or maybe I'd buy too much. But I ultimately decided that this was my first time. I was bound to have some successes and some failures. If I didn't try, though, I'd be annoyed.

Also: If you can, try to do this shopping trip alone. I asked Stephen to watch the kids because I wanted to concentrate and get things right. I think if I was wearing Eloise or having to tend to Ada, I may have gotten off track. Our Wegmans has a great kids space with free babysitting I may use in the future if Eloise is napping and Ada wants to come along for some of the ride.


Final notes:


I spent a grand total of $298 of my $350 monthly food budget this weekend. And actually $20 of this was on food for our Weekend Fund, so I still have just about $70 left of the monthly budget along with all of the $150 for the weekly stuff I divide up. I hope to not spend all of this and maybe pitch more to paying off our debt.

I'll be back with more thoughts and a video about the shopping experience -- as well as my review of the new cash envelope system I purchased on Etsy.

Read more...
Related Posts Plugin for WordPress, Blogger...
About This Blog

MyFreeCopyright.com Registered & Protected

© 2009-2014 by the (never home)makers
All content on this blog is copyrighted.

Want to publish our pics, tips, or tricks?
Contact us! [neverhomemaker@gmail.com]

We value transparency. Links on this page may contain affiliates. In addition, please see our disclosure policy regarding sponsored posts.

  © Blogger template Simple n' Sweet by Ourblogtemplates.com 2009

Back to TOP  

Blogging tips